
Short Term Financing: Meaning, Types, Sources, Examples, and 2026 Rates | Corporate Finance
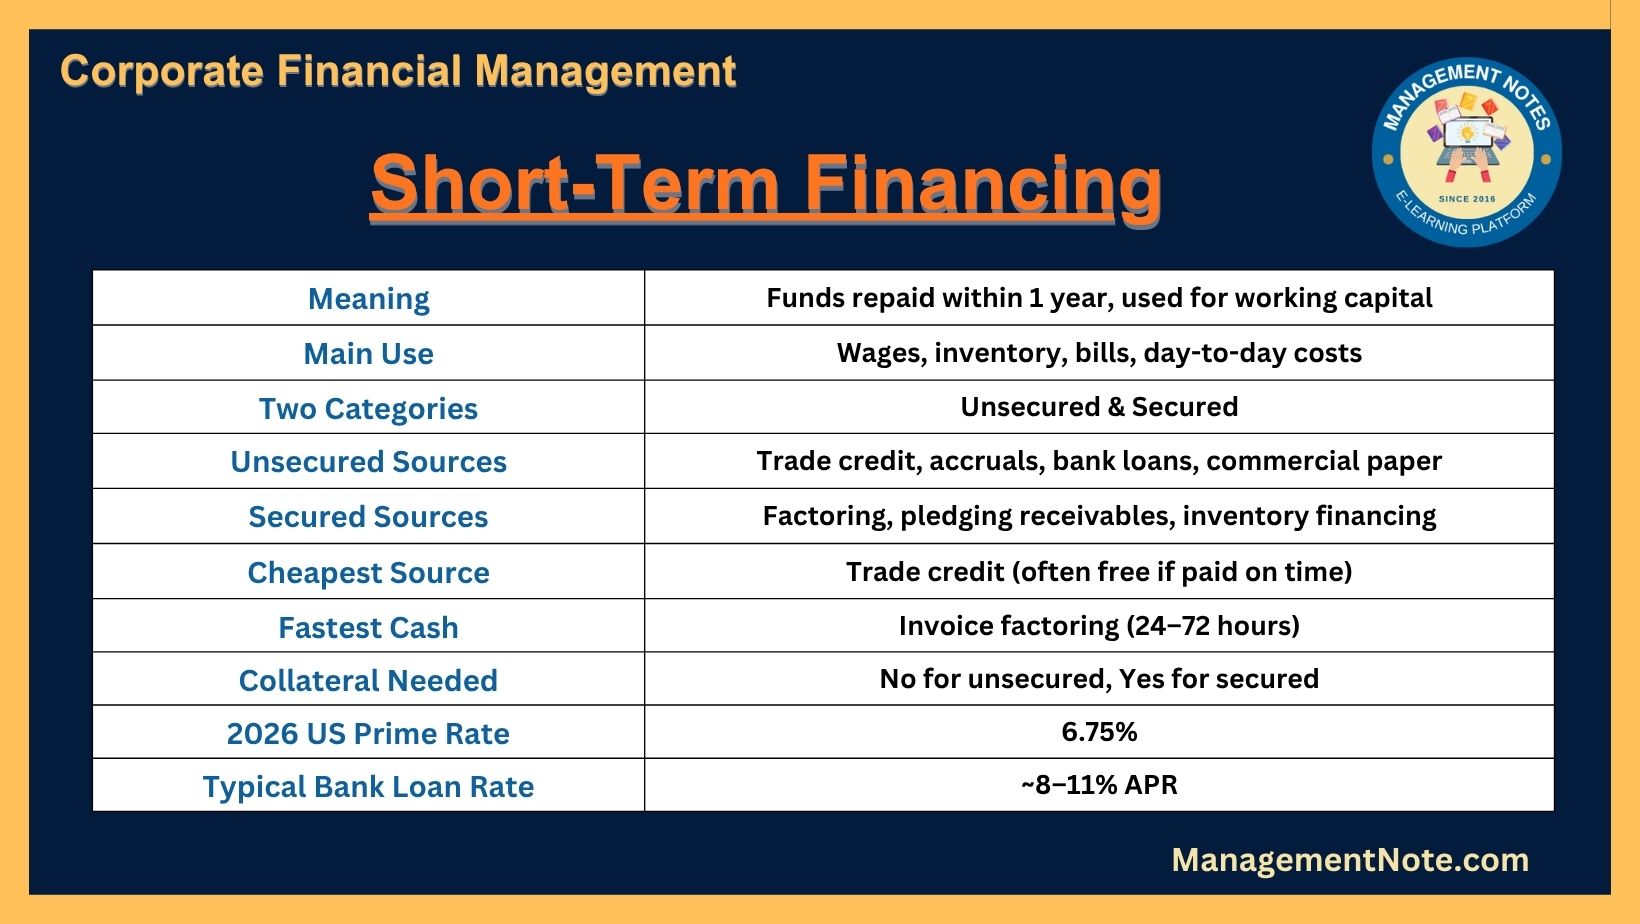
Short-term financing is money a business borrows or arranges that must be paid back in one year or less. Companies use it to pay for daily costs like raw materials, wages, and bills.
This guide explains what short-term financing means, why firms use it, every major type and source, real 2026 interest rate data, and answers to the most searched questions on this topic.
Quick Summary Table
| Question | Short Answer |
|---|---|
| What is short-term financing? | Funds a business must repay within 12 months, used mainly for working capital |
| Main goal | Keep daily operations running (raw materials, wages, bills) |
| Two big groups | Unsecured sources and secured sources |
| Cheapest common source | Trade credit (often no interest if paid on time) |
| Most flexible source | Bank line of credit |
| Riskiest part | Missing a payment can trigger legal trouble faster than long-term debt |
| Typical 2026 short-term bank borrowing cost (US) | Roughly 8%–11% APR, based on the Prime Rate of 6.75% plus a lender margin |
What Is Short-Term Financing?
Short-term financing means all the money a firm owes that is due for repayment within one year. Businesses use it to fund their working capital, which is the cash needed to run daily operations. It is also called current liabilities financing or working capital financing.
Firms use short-term financing to pay for things like:
- Buying raw materials and inventory
- Paying salaries and wages
- Covering rent, utilities, and other bills
- Managing gaps between paying suppliers and getting paid by customers
How much a firm needs, and which source it picks, depends on its size, its industry, its cash flow pattern, and how the market prices risk at that time. The main rule of thumb is simple: pick the source with the lowest cost and risk that still fits the firm’s needs and policies.
Characteristics of Short-Term Financing

Short-Term Financing Vs Long-Term Financing

Advantages of Short-Term Financing

Disadvantages of Short-Term Financing

Sources of Short-Term Financing (Full Classification)
Short-term financing sources fall into two broad groups: unsecured sources and secured sources. Unsecured sources are split into spontaneous and non-spontaneous sources. Secured sources are split into accounts receivable financing and inventory financing.
Short-Term Financing
│
├── A. Unsecured Sources (no collateral needed)
│     ├── Spontaneous: Trade Credit (Accounts Payable), Accrued Expenses
│     └── Non-Spontaneous: Bank Loans & Lines of Credit, Commercial Paper
│
└── B. Secured Sources (collateral required)
      ├── Accounts Receivable Financing: Pledging, Factoring
      └── Inventory Financing: Floating Lien, Chattel Mortgage, Trust Receipt Loan,
          Field Warehouse Receipt Loan, Terminal Warehouse Receipt Loan
A. Unsecured Sources of Short-Term Financing
Unsecured sources do not need any collateral. A firm with a strong credit history usually qualifies for these. Because there is no asset backing the loan, lenders take on more risk, so they often charge higher fees or interest to firms with weak financial records.
Even without collateral, both the lender and the borrower still benefit: the business gets fast cash, and the lender earns interest.
A1. Spontaneous Sources
Spontaneous sources grow automatically as a business grows. A firm does not need to negotiate for them separately; they appear naturally from daily operations.
1. Trade Credit (Accounts Payable)
Trade credit happens when a supplier lets a business buy goods now and pay later, usually in 30, 60, or 90 days. It is the single largest source of short-term funding for most companies because it is simple and often has no direct interest cost if paid within the agreed term.
Many suppliers offer an early payment discount, such as “2/10 net 30,” which means a 2% discount if paid within 10 days, or full payment due in 30 days. Skipping that discount has a real cost, since the business is effectively paying a high annual rate just to hold the cash a little longer.
2. Accruals (Accrued Expenses)
Accruals are expenses a company owes but has not yet paid, such as unpaid wages, unpaid taxes, or unpaid interest. These build up naturally between pay periods and cost the firm nothing extra, making them one of the cheapest forms of short-term financing available.
Summary Table: Spontaneous Sources
| Source | Collateral Needed | Typical Cost | Speed | Best For |
|---|---|---|---|---|
| Trade credit | No | Free if paid on time; high cost if discount is skipped | Immediate | Buying inventory and supplies |
| Accruals | No | Free | Automatic | Covering wages, taxes, and interest between due dates |
A2. Non-Spontaneous Sources
Non-spontaneous sources must be arranged and negotiated with a lender. They do not grow automatically with the business.
1. Bank Loans and Lines of Credit
A short-term bank loan is money borrowed from a bank and repaid within a year, often through a single payment or in scheduled installments. A line of credit is a preset borrowing limit a business can draw from and repay as needed, similar to a credit card for a company.
As of mid-2026, the US Prime Rate stands at 6.75%, following the Federal Reserve holding its benchmark federal funds rate at 3.50%–3.75% through its 2026 meetings.
Banks generally price short-term business loans and lines of credit at Prime plus 1 to 4 percentage points, depending on the borrower’s credit and relationship with the bank, which puts typical short-term working capital borrowing costs in the range of roughly 8% to 11% APR for well-qualified businesses in 2026.
2. Commercial Paper
Commercial paper is a short-term, unsecured promissory note issued mainly by large, financially strong companies to raise cash quickly, usually for 1 to 270 days. It is cheaper than a bank loan but is only available to companies with a strong credit rating, since there is no collateral backing it.
According to Federal Reserve H.15 data, the 60-day AA-rated nonfinancial commercial paper rate was about 3.72% in July 2026, showing how much cheaper this option is for top-rated firms compared with a typical small business bank loan.
Summary Table: Non-Spontaneous Unsecured Sources
| Source | Collateral Needed | Who Qualifies | Approx. 2026 Cost | Speed |
|---|---|---|---|---|
| Bank loan / line of credit | No | Most businesses with decent credit | Roughly 8%–11% APR (Prime + margin) | Days to a few weeks |
| Commercial paper | No | Large, highly rated corporations only | Roughly 3.6%–4% (AA-rated, 60-day) | Fast, but only for qualified issuers |
B. Secured Sources of Short-Term Financing
Secured sources need collateral, usually accounts receivable or inventory. These sources are useful for firms that do not have a strong enough credit rating to qualify for unsecured financing. Because the lender has an asset to fall back on, firms with weaker credit histories can still raise cash this way.
B1. Accounts Receivable Financing
This method uses unpaid customer invoices (accounts receivable) as the basis for raising short-term cash.
1. Pledging Accounts Receivable
Pledging means a business uses its receivables as collateral for a loan while still owning and collecting on those invoices itself. The lender advances a percentage of the receivable value, commonly 70% to 90%, and charges interest plus a service fee.
2. Factoring Accounts Receivable
Factoring means selling invoices outright to a company called a factor. The factor takes over collecting payment from customers and pays the business most of the invoice value upfront, minus a fee.
In 2026, invoice factoring fees typically range from about 1% to 5% of invoice value, with advance rates commonly between 80% and 95%, depending on the customer’s credit quality, the industry, and how fast customers usually pay.
Because factoring fees are charged over a short period, such as 30 days, the effective annual cost can look much higher than the headline rate suggests, sometimes reaching 30% to 60% APR if customers are slow to pay.
Summary Table: Accounts Receivable Financing
| Method | Who Owns the Invoice | Who Collects Payment | Typical Advance | Typical 2026 Cost |
|---|---|---|---|---|
| Pledging AR | The business | The business | 70%–90% of invoice value | Interest plus a service fee |
| Factoring AR | The factor (buyer) | The factor | 80%–95% of invoice value | About 1%–5% per invoice cycle |
B2. Inventory Financing
Inventory financing uses stored goods, raw materials, or finished products as collateral for short-term funds. This is common for firms with large amounts of physical stock but weaker cash flow.
1. Floating Lien
A floating lien gives the lender a claim over a firm’s entire inventory as a group, without needing to identify specific items. As old stock sells and new stock arrives, the lien automatically covers the new inventory too. This is convenient but offers the lender less control over any single item.
2. Chattel Mortgage
A chattel mortgage is a loan secured by specific, identified pieces of movable property, such as named equipment or clearly listed inventory items. Unlike a floating lien, the exact items pledged are fixed, and the business cannot sell them without the lender’s approval unless the loan is repaid.
3. Trust Receipt Loan
Under a trust receipt loan, a lender releases specific, identifiable, and often serial-numbered goods (common with cars, appliances, and machinery) to the business to sell, while keeping legal ownership until the loan is repaid. As each item sells, the business must pay back the loan portion tied to that item, a system often called “floor plan financing” in car dealerships.
4. Field Warehouse Receipt Loan
In this method, a public warehouse company sets up a secured storage area right on the business’s own property. The warehouse company controls access to the goods, and only releases inventory once the business pays down part of the loan. This lets the firm keep goods close by while still giving the lender real control.
5. Terminal Warehouse Receipt Loan
Here, the pledged goods are moved off-site to a public warehouse away from the business’s own location. The warehouse issues a receipt showing the lender has a claim over the stored goods. This method gives the lender the strongest control since the business cannot access the goods directly, but it adds transport and storage costs.
Summary Table: Inventory Financing
| Method | Collateral Control | Goods Location | Best For |
|---|---|---|---|
| Floating lien | Low (covers whole inventory in general) | Stays with the business | Firms with fast-moving, mixed inventory |
| Chattel mortgage | Medium (specific items named) | Stays with the business | Firms with fixed, identifiable equipment or stock |
| Trust receipt loan | Medium-high (item by item release) | Stays with the business, tracked by item | Car dealers, appliance and machinery sellers |
| Field warehouse receipt loan | High | Stays on the business’s property, in a locked section | Firms needing quick access to their own goods |
| Terminal warehouse receipt loan | Highest | Moved to an outside warehouse | Lenders wanting maximum control over the collateral |
Master Summary Table: All Types of Short-Term Financing
| Type | Category | Collateral Needed | Typical Cost Level | Speed to Arrange | Best Suited For |
|---|---|---|---|---|---|
| Trade credit | Unsecured, spontaneous | No | Very low to free | Immediate | Everyday purchases from suppliers |
| Accruals | Unsecured, spontaneous | No | Free | Automatic | Wages, taxes, interest due soon |
| Bank loan / line of credit | Unsecured, non-spontaneous | No | Moderate (roughly 8%–11% APR in 2026) | Days to weeks | General working capital needs |
| Commercial paper | Unsecured, non-spontaneous | No | Low, for top-rated firms only | Fast for large firms | Large corporations with strong credit |
| Pledging accounts receivable | Secured | Yes (receivables) | Moderate | Days | Firms with steady, creditworthy customers |
| Factoring accounts receivable | Secured | Yes (receivables sold) | Higher (1%–5% per cycle) | Fast, 24–72 hours | Firms needing very fast cash from unpaid invoices |
| Floating lien | Secured | Yes (general inventory) | Moderate | Moderate | Businesses with changing stock levels |
| Chattel mortgage | Secured | Yes (named items) | Moderate | Moderate | Businesses with fixed, identifiable assets |
| Trust receipt loan | Secured | Yes (item by item) | Moderate to high | Moderate | Dealers selling serial-numbered goods |
| Field warehouse receipt loan | Secured | Yes (on-site controlled) | Moderate to high | Moderate | Firms needing quick access to stored goods |
| Terminal warehouse receipt loan | Secured | Yes (off-site) | Highest | Slower | Lenders needing full control of collateral |
How to Choose the Right Source of Short-Term Financing
Check the cost first. Compare the real annual cost, not just the headline rate, since fees like factoring charges can look small but add up fast.
Match the source to the need. Use trade credit and accruals for routine costs, and use secured sources like factoring only when cash is urgently needed.
Look at your credit standing. Strong credit opens the door to cheaper unsecured sources; weaker credit often means turning to secured, collateral-based options.
Think about renewal risk. A source that a lender can cut off suddenly is riskier than one with steady, predictable terms.
Watch the total relationship cost. Include setup fees, service charges, and minimum volume fees, not just the interest or discount rate.
Real-Life Example
A small furniture manufacturer needs $50,000 to buy wood and fabric before a big holiday order. It has unpaid customer invoices worth $70,000 that are due in 45 days. Instead of waiting, the firm sells those invoices to a factoring company at a 3% fee and receives 85% of the invoice value upfront.
This gives it the cash it needs today, while the factoring company collects payment from the furniture firm’s customers later. This is a classic real-world use of accounts receivable factoring, a type of secured short-term financing.
2026 Short-Term Financing Rate Snapshot (United States)
| Rate Type | Approximate 2026 Level | Source |
|---|---|---|
| US Prime Rate | 6.75% (held through 2026 FOMC meetings) | Federal Reserve / FOMC policy data |
| Federal funds target range | 3.50%–3.75% | Federal Reserve |
| 60-day AA nonfinancial commercial paper | About 3.7% (July 2026) | Federal Reserve H.15 release |
| Typical small business short-term loan APR | Roughly 8%–11% | Based on Prime plus common lender margins |
| Invoice factoring fee | About 1%–5% per invoice cycle | Industry factoring rate data |
Rates change often. Always confirm the current rate with your bank or lender before making a financing decision.
Frequently Asked Questions About Short-Term Financing
What is short-term financing in simple words?
Short-term financing is money a business borrows and must pay back within one year. It is mainly used to cover daily costs like wages, supplies, and bills.
What are the main sources of short-term financing?
The main sources are trade credit, accrued expenses, bank loans and lines of credit, commercial paper, accounts receivable financing (pledging and factoring), and inventory financing (floating liens, chattel mortgages, trust receipt loans, and warehouse receipt loans).
What is the difference between short-term and long-term financing?
Short-term financing is repaid within a year and funds daily operations. Long-term financing is repaid over several years and funds large investments like buildings or equipment.
Is short-term financing riskier than long-term financing?
Yes, in one key way. If a firm misses a short-term payment, it can quickly face serious legal and credit problems, while long-term debt gives more time to recover from a rough patch.
What is the cheapest source of short-term financing?
Trade credit is usually the cheapest, since it often carries no direct cost if the invoice is paid within the agreed period. Accrued expenses are also cost-free but are automatic rather than something a business can request more of.
What is factoring accounts receivable? Factoring is when a business sells its unpaid customer invoices to a factoring company for immediate cash, usually receiving 80% to 95% of the invoice value upfront, minus a fee of about 1% to 5%.
Why do small businesses use short-term financing?
Small businesses often face uneven cash flow, seasonal demand, or slow-paying customers. Short-term financing bridges these gaps so the business can keep paying bills and buying stock on time.
Does short-term financing require collateral?
Not always. Unsecured sources like trade credit, accruals, bank loans, and commercial paper generally do not require collateral. Secured sources like factoring, pledging receivables, and inventory-based loans do require collateral.
What is the current cost of short-term business borrowing in 2026?
As of mid-2026, the US Prime Rate is 6.75%, and typical short-term bank borrowing for small businesses runs roughly 8% to 11% APR, while top-rated large firms can borrow through commercial paper at around 3.7%.
What is a trust receipt loan used for?
A trust receipt loan is commonly used by dealers who sell serial-numbered goods like cars or appliances. The lender keeps ownership of the goods until they are sold, and the dealer repays the loan as each item is sold.
Sources
- Federal Reserve, H.15 Selected Interest Rates (Commercial Paper) – federalreserve.gov
- FedPrimeRate.com, United States Prime Rate history and FOMC updates
- Britannica Money, Short-term financing overview
- Federal Reserve Bank of St. Louis (ALFRED/FRED), Commercial Paper series (CPF2M, CPN2M)
- Industry data on invoice factoring rates and fees, 2026 publications
Similarly, You may also like:
- Inventory Financing – Methods of Inventory Financing | Short Term Financing
- Difference between Short term and Long term financing | Corporate Finance

MBA- Finance Specialization
I am Smirti Bam, an enthusiastic edu blogger with a passion for sharing insights into the dynamic world of business and management through this website.
I hold a MBA degree from Presidential Business School, Kathmandu, and a BBA degree with a specialization in Finance from Apex College,
- Onboarding Vs. Orientation: Key Differences, Benefits, Process & Best Practices | Human Resource Management (HRM) - September 24, 2026
- Moonlighting Vs Freelancing: Meaning, Differences & Risks Explained | Human Resource Management (HRM) - September 14, 2026
- Employee Retention Vs. Employee Engagement: Key Differences Explained | Human Resource Management - September 6, 2026


short term financing